

In 2021, I left my cushy job as a Director of Acquisitions at someone else’s investment fund to go build a new fund, entirely from scratch. We raised some money, I built the underwriting model, and got to work. Five years, $1 billion, and 2,000 closings later, we had built an investment fund, and we still used the same model on the last day that I had built on the first day. It worked! It got a couple upgrades, as all things do over time, but it was still essentially the same underwriting model we started with.
Why this model matters
Big investment funds build models, including this one, to make sure they do not overpay for anything. I know some of you will say “oh, but the big hedge funds DID overpay for property back in my market in 2022” to which I say - the big institutional investment funds might have paid more than you would have, but they were able to raise billion of dollars from investors and buy thousands of properties and earned some pretty great returns along the way. How did they know that it would work? How did they know which properties were relatively undervalued and which would produce the returns they needed? This model.
Private equity funds spent thousands of dollars paying full time analysts to build these models from scratch. I was that guy, and I got paid $8,300 to build this model for my last fund - and now I’m handing it to you for the grand sum of $0 dollars.
Watch this video and I’ll walk you through how it works, why it works that way, and how you can use it to make money buying investment property.
What does this model actually do?
At it’s core, this model answers one question - What is this property actually worth, to me? Not what does the seller want, or what does Zillow’s broken algorithm think it is worth, and not what some “expert” on Bigger Pockets thinks you can get for it.
What can I pay for this, and get the return I need?
This model takes the things you know about the property - purchase price, rent, property taxes, financing terms, renovation costs, and a bunch of assumptions, bumps them all together and spits out the things you should actually care about - cash flow, yield, profit, and returns.
It shows you what happens if rent ends up being $100 less than you thought it would be, or if the renovation is $10,000 more than expected, or if you get a screaming deal and buy it for 20 grand less than you thought you’d have to pay. This is how institutional investors look at deals. You don’t need to be a Blackstone trained genius, you just need a consistent framework to help you make decisions.
I was paid $8,300 to build this model for my last fund, and I’m giving you a copy for free.
Subscribe to The Comps and I’ll send it to you. Every post comes with something genuinely useful — models, datasets, calculators, frameworks, and other tools I’ve actually used. And I promise I won’t spam you with AI-generated garbage.
Key Formulas and Investment Concepts
If your heart started fluttering when I was talking about formulas, math, and financial returns, then read on, fellow nerd.
To get the most out of this model, you’ll need to understand some of the financial metrics I used. These are standard across real estate investment - learn them once and they’ll serve you forever. Yes, there’s math involved. I’m not sorry.
Net Operating Income (NOI)
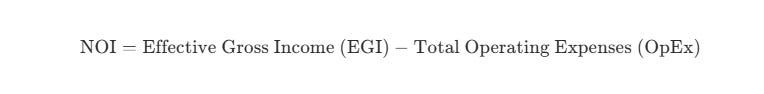
NOI is a measure how how much money you make, after expenses, on an investment. If you lease out a property for $1,000/month and pay $100 in total expenses each month (utilities, property manager, etc), your EGI was $1,000, but you actually only made $900 - your NOI.
Note - debt service, capital expenditures (capex), taxes, and a couple other things are intentionally excluded from Opex because they are NOT Opex. They go “below the line”, the “line” being NOI. You can have an investment that makes $900 in NOI and loses money every month. If your stuff ain’t working, don’t buy more until you figure it out. Write that down, it’s pretty wild how many people I’ve seen making this rather obvious sounding mistake.
Capitalization Rate (Cap Rate)
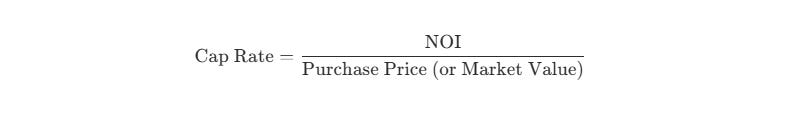
Note 1 - cap rate is a measure of returns - I use this to quickly compare unlevered yields across different properties and markets. I can buy a house in Phoenix at a 4.8% cap rate, and a house in Birmingham at a 6.8% cap rate - I get more money each month, relative to how much I spent on it, in Birmingham, than I do in Phoenix.
Note 2 - cap rate is a measure of risk - the reason why you might be willing to buy a property in Phoenix for 100k knowing you’ll only get 4.8k in NOI each year when you could spend the same 100k in Birmingham and get 6.8k in NOI each year is because Phoenix is a bigger, less risky market, with more demand to buy that house back from you, later on. Theoretically, you’re more likely to have issues of some kind in Birmingham than you are in Phoenix. Lower cap rates imply a less risky investment.
Internal Rate of Return (IRR)
If “profit” is a way of measuring how much money you make, then IRR is a measure of how fast you make that money.
Example: you make a 20k profit on a 100k investment deal (hypothetically you bought it for 80k, invested 20k into renovations, and sold it for 120k), that’s great! Actually it’s only great if you did that in less than 1 year - that would be a 20% IRR (20% profit). If it took you 5 years, your IRR is only 3.7% - not so good. Super simplified, it’s the annual interest rate you earn for every dollar you invested, but adjusted to reflect the Time Value of Money.
If you are a math nerd like me, IRR is formally defined as the discount rate that sets the Net Present Value (NPV) of all cash flows equal to zero. You will never need to be able to reproduce this in real life, with the only exception being possibly a hiring interview if you want to work at Blackstone or if you’re in a Real Estate Financial Modeling 310 course at your favorite University. Go Cougars!
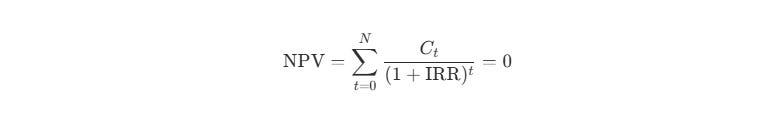
Unlevered IRR measures the return on the asset’s cash flows assuming 100% cash purchase, ignores debt.
Levered IRR measures the actual return on equity after accounting for debt service and loan principal paydown at exit.